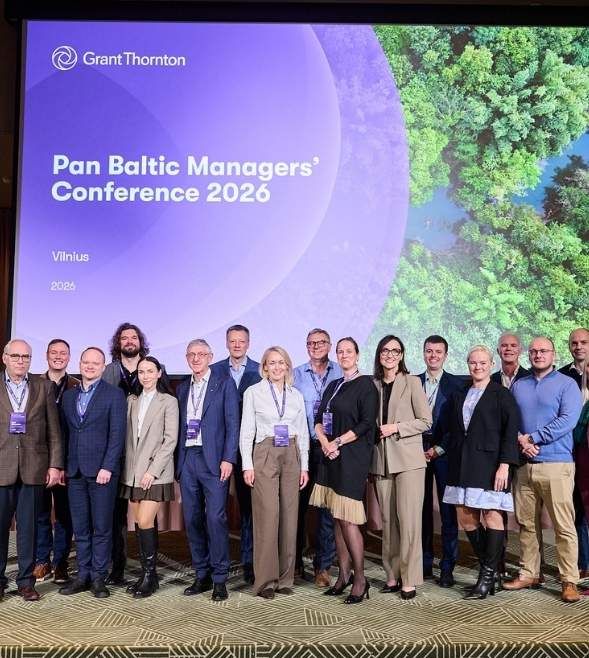
Grant Thornton Baltic’s annual leadership conference took place in Vilnius, bringing together partners and service line representatives from Latvia, Lithuania and Estonia. On the first day, working groups discussed the development priorities of each service line; on the main conference day, participants shared their conclusions and agreed on priorities for future collaboration.
Showing 16 of 39 content results
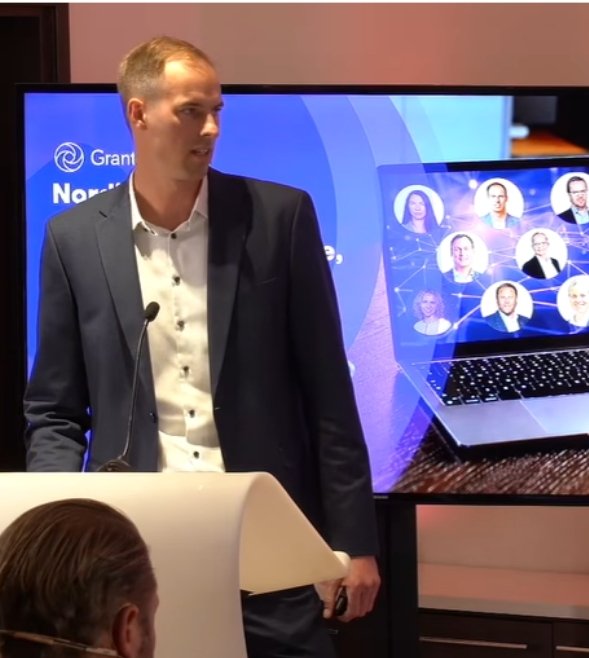
The seminar “Nordic-Baltic Tax Outlook 2025–2026: Tax Authority Practice, Case Law and Legislative Outlook” took place in Tallinn, attracting an audience of more than 400 participants interested in the latest tax developments and upcoming changes across the Nordic-Baltic region.
As of 01.01.2026, amendments to the Law on Taxes and Duties will come into force. Their purpose is to simplify transfer pricing documentation requirements and reduce the administrative burden on taxpayers. The amendments relate to transactions conducted from the reporting year 2025 onwards.
Kaspars Strazds is responsible for efficient and business-driven management of transfer pricing projects for local and international clients.
Grant Thornton Baltic has been named a finalist in the ITR Europe Tax Awards 2026, an awards competition organised by the international tax publication International Tax Review (ITR).
As of 01.01.2026, amendments to the Law on Taxes and Duties will come into force. Their purpose is to simplify transfer pricing documentation requirements and reduce the administrative burden on taxpayers. The amendments relate to transactions conducted from the reporting year 2025 onwards.
In 2026, significant tax changes come into effect across the Baltic States. This overview highlights the main updates in Latvia, Lithuania and Estonia – from income tax and VAT to social contributions and excise duties – helping businesses plan their tax obligations effectively.
Discover the Upcoming Tax Changes in Latvia for 2026 and Be Ready for the Year Ahead!
In the beginning of the year, several tax changes were introduced in Estonia, Latvia and Lithuania.
Changes in taxation, effective as of 1 January, 2022
Thin-capitalization rules are Abolished in 2021 and 2022